Category: Uncategorized

  • RADAR FY2024 – Strongest result in more than 10 years, but insurers in regulator sights

    How is the general insurance industry tracking? Find out in Taylor Fry’s latest annual report, as we share our insights on all the major happenings, trends and impacts on the market in our class-by-class analysis.

    For the second year in a row, the industry posted a healthy profit – $3.9 billion after tax – over the nine months* to 30 June 2024. But the solid result comes alongside a sharp focus on industry integrity, with customers and climate the big issues.

    Drawing on data from the Australian Prudential Regulatory Authority (APRA), we reveal the healthy industry performance was driven by three main influences – premium increases broadly matching claims costs, catastrophic losses below expectations and steady investment returns of $3.4 billion, up $0.8 billion on last year.

    Here’s a snapshot of key themes we explore in RADAR FY2024 …

    Focus on transparency, accountability and customer treatment

    Actuary and Principal Scott Duncan explores the positive figures against a backdrop of heightened ethical focus. “Some of the key themes driving future industry performance will be transparency, accountability and the fair treatment of all customers,” he says. “The most recent example is the guidance from the Parliamentary inquiry into insurers’ responses to 2022 major floods claims, with its three Ps – policyholder treatment, pooling mechanisms and prioritising preparation.”

    Flood inquiry affects whole industry

    “Many of the recommendations arising from the inquiry are relevant outside home insurance and the industry is actively considering what this means for other products and processes,” he adds. “As part of the increased focus on customers, senior management and Boards are increasingly demanding information on customer outcomes to complement the usual metrics on financial performance.”

    Climate and the race for new technology

    Looking ahead, the rapid uptake of AI in business and its climate implications illustrate that the risks insurers face and manage are evolving quickly. “The rise in AI has led to a greater demand for energy, which must be considered in the world’s path to net zero greenhouse gas emissions,” Scott says.

    “Insurers investing heavily in AI for business transformation goals will need to consider how this fits in with their net-zero targets and transition planning. They can’t afford not to pay close attention to the shifting landscape, their role within it and the impact on the cover they offer.”

    Customers, AI and climate are among the big themes this year, with regulators focused on integrity.

    Addressing physical risks only part of the story

    He adds that for the industry, building understanding involves recognition that physical risks arising from climate change are only part of the story, that minimising the causes – transitioning to a low carbon economy – is critical to a sustainable insurance future.

    “The transition to net zero is undoubtedly changing the risks insurers face and manage,” Scott says. “For example, lithium-ion battery fires and liability exposure from withdrawing too slowly from carbon-intensive industries are top of mind for insurers. But plenty of opportunities exist for insurers within this evolving landscape to innovate and drive the move to a more environmentally and socially responsible society.”

    Underinsurance a stark reality

    Diving into the classes, the RADAR report shows consumers appear to be turning away from home insurance as cost-of-living pressures bite, with the number of risks insured retreating by around 3% compared with last year. “This is the largest year-on-year drop in insured risks since at least 2013, and follows a 19% year-on-year increase in average written premium,” Scott says. “The growing political focus means insurers must engage more actively with regulators. By providing insights into the practicalities of climate risk pricing, insurers can help shape future regulations, balancing affordability with risk sensitivity.”

    Future profitability, he says, will depend on “the level of catastrophic activity and whether recent price increases are sufficient to cover the increase in claims costs, particularly as labour shortages for skilled workers continue to increase repair costs”.

    As regulatory changes and media attention on the industry grow, maintaining a positive reputation will be crucial, Scott adds. “Demonstrating a commitment to customer value and community protection, for example through resilience initiatives, will be vital for preserving trust and loyalty.”

    The transition to net zero is undoubtedly changing the risks insurers face and manage … But plenty of opportunities exist for insurers within this evolving landscape to innovate and drive the move to a more environmentally and socially responsible society.

    Technology changing the nature of car repairs

    Turning to Domestic Motor, he says the technology embedded in new vehicles and the shift to electric vehicles are changing the nature of repairs for the industry. “While the cost of spare parts and accessories may have peaked, repair costs are on the rise due to labour shortages and increases in repair times.”

    LMI reaps rewards

    Reserve releases are another area of interest in RADAR FY2024, which reveals these have had a large impact on 2024 industry performance, with several classes benefitting from a reassessment of prior year claims costs. “Lenders mortgage insurance is a standout class, as the reserves built early in the pandemic continue to be released,” Scott says. “LMI insurers haven’t seen the increase in claims they were expecting due to property price increases, low unemployment and government support during COVID-19.”

    The rapid uptake of AI and its climate implications illustrate the risks insurers face are evolving.

    Silent AI follows silent cyber

    Reflecting on the lessons learned from silent cyber, the Taylor Fry report observes insurers are “getting on the front foot” to clarify coverage and build out underwriting requirements to include questions on the use of AI. “The insurance industry is no stranger to AI and is well versed in the opportunities offered by AI and the potential risks,” Scott says. “The focus now is on understanding the opportunities for new products and how AI changes the risk landscape for existing products.”

    *The latest APRA data excludes the September 2023 quarter due to changes in reporting standards.

  • Increase in Australians with disability – new ABS survey

    For more than 15 years, the number of people who report having disability has been stable – between 4 and 4.5 million – until now. New data released by the Australian Bureau of Statistics reveals the figure has increased to 5.5 million. We discuss these latest findings and offer some key takeaways for policymakers.

    The results of the ABS 2022 Survey of Disability, Ageing and Carers (SDAC) show the number of people with disability rose by 25% from 2018 to 2022. The increase affected most cohorts, but was particularly high for young people and for people with severe or profound disability.

    In the survey, the rate of increase in people with disability was highest for young people aged 0-24

    What do we mean by ‘disability’?

    Under ABS definitions, a person has a disability if they have “any limitation, restriction or impairment which restricts everyday activities and has lasted, or is likely to last, for at least six months”. ABS estimates of disability include:

    • People with severe or profound disability. People in this group sometimes or always need support with activities such as self-care, mobility or communication. It’s likely many NDIS participants fall into this group.
    • People with milder disabilities, many of whom are unlikely to be eligible for the NDIS.

    A closer look at the numbers

    As we mentioned, the total number of people with disability has held steady between 4 and 4.5 million (the dark blue line in the chart), since 2009. In 2022, it rose fairly sharply to 5.5 million.

    The rate of increase was higher for severe or profound disability, although there was still a higher increase in the number of people with milder disability than in previous years.

    In 2022, the number of people with disability rose fairly sharply, after a long period of stability

    This next chart shows the proportion of Australians in each age group who have disability. Expressing the number of people with disability as a proportion of population allows comparison between age groups.

    Overall, the chart shows more people had a disability in 2022 than 2018 across all age groups. The rate of increase was highest for young people aged 0-24. For people aged 25 and above, the rate of disability had been slowly reducing until 2018, but this trend reversed in 2022.

    Consistent with past surveys, more than half of people aged over 65 have a disability, as some conditions such as physical disabilities and Alzheimer’s Disease become more common as we age.

    The share of those with disability aged 25+ was reducing until 2018. In 2022, the trend reversed

    What’s driving the increase?

    The ABS identifies four potential drivers of the increase observed in this year’s SDAC:

    • A growing awareness of disability in Australia
    • A general increase in prevalence of some disabilities or long-term health conditions
    • An ageing population
    • An online, self-completion questionnaire being offered as an option for the first time in 2022.

    While it’s not possible to estimate the extent of contribution from each factor, we can make some general observations:

    • There’s good reason to think awareness of disability would have increased since the last survey (2018). Back then, the NDIS was only part way through its roll-out around Australia. It makes sense that, by 2022, with a fully implemented national scheme and increased media attention, awareness of disability may have increased.
    • The number of Australians with autism has increased – but more detailed analysis is needed to understand increases in other disabilities or health conditions. The 2022 survey showed a 40% increase in the number of people with autism in Australia, compared to 2018. This aligns with experience in the NDIS – the scheme has seen high growth in the number of people with autism applying each year. While data on other disability types isn’t included in the ABS summary of the survey, more detailed analysis could be undertaken in future to understand how different disabilities contribute to the increase.
    • The ageing population is relevant, but not the sole driver of the increase. We know this because the increase has affected younger as well as older people with disability.
    • The ABS has given participants a new way to respond to its survey – an online option – and the impacts of this are unknown. For example, if the ABS online survey made people feel more comfortable disclosing they have a disability, this may have contributed to the increase.

    Some key takeaways for policymakers

    Among important considerations for policymakers, we’ve identified:

    • For the NDIS, the survey lends weight to the argument that some of the growth seen to date has reflected increased recognition of disability in the wider community. Unfortunately, the survey won’t tell us what many people want to know – whether or when we might see a slowing of growth in the NDIS.
    • The recent NDIS Review also recommended strengthening supports outside the NDIS for people with disability, recognising that there is a large group of people with disability outside the NDIS who would benefit from more support. The results of this survey indicate there may be more people who would benefit from these supports than previously thought.

    Other survey findings

    The SDAC produced a wide range of other important findings – much more than we could cover in this brief article – including:

    • Information on employment, health, wellbeing and other outcomes for people with disability. For example, the survey shows people with disability have benefitted from the reduced unemployment rate experienced by other Australians in 2022.
    • For the first time, information on the number of people with disability who have experienced abuse or neglect (complementing the results of other surveys such as the ABS Personal Safety Survey). The SDAC found 11.4% of adults with disability experienced at least one form of physical abuse, emotional abuse or neglect in the past 12 months – underscoring the findings of the Disability Royal Commission in 2023.

    For more detail on these and other findings, visit the ABS website.

  • Elevated premiums and profits – what’s really going on in New Zealand?

    With news stories firmly focused on affordability, plus a recent period of benign weather in NZ, a perfect storm may be brewing, as community experience and insurer bottom lines collide. What’s behind the headlines and how did we arrive here? We spoke with Ross Simmonds to find out and explore the impact for insurers.

    As premiums rise, underinsured homeowners or those opting to go without insurance may also increase

    Rising premiums have been a global issue for some time. What’s the latest on the horizon for the New Zealand insurance market?

    From a claims perspective, it’s likely insurers will report significant profits in 2024 – with the costs of natural disasters lower than expected and Tower already upgrading its profit expectations for the year. Insurance Council of New Zealand (ICNZ) data shows the last natural disaster resulting in significant insurance claims was more than a year ago, although the weather events last week in East Cape are likely to break this run.

    Why is this experience not reflected in reduced premiums?

    Insurance is a complicated balancing act. Insurers set their premiums assuming a level of claims based not on one year’s experience but on the frequency of natural disasters over many years – and in the past decade or so each year has averaged seven to eight events.

    Understandably, the community may be concerned about premium affordability and whether insurers have over-corrected. But a single large natural disaster, such as an earthquake or cyclone, can be the difference between a good year and a bad year – which means insurers need to look at claims over a long period.

    What other trends are you seeing?

    The other major change has been the introduction of risk-based pricing for flood risks. The Auckland floods and Cyclone Gabrielle in 2023 highlighted the widespread damage flood can cause. Risk-based pricing involves using sophisticated models to identify houses most likely to be affected by a flood. This can create hikes in premiums for properties most at risk, even without any recent claims.

    What role does reinsurance have in this environment?

    The RBNZ, which regulates insurers in Aotearoa, requires insurers to hold high levels of reinsurance to spread the cover for large losses arising from earthquakes. This reflects the high level of seismic risk Aotearoa faces. While the Earthquake Commission (EQC) provides cover for the first $300k, most houses are insured for more. Insurers are required to purchase reinsurance for this additional cover, making reinsurance costs a big component of the outlay for Aotearoa insurers. Based on ICNZ statistics, reinsurance is roughly one-third of the premium for home and contents policies.

    … a single large natural disaster, such as an earthquake or cyclone, can be the difference between a good year and a bad year – which means insurers need to look at claims over a long period.

    What are the most challenging areas to navigate for the industry?

    Affordability is the key issue. There’s a natural tension between insurers wanting to improve their understanding of the risks they face in providing cover to Kiwis against policyholders wanting affordable insurance. For example, as insurers learn more about flood risk, the cost of insurance for high-risk properties becomes unaffordable. Given it’s difficult for an individual property owner to reduce flood risk, they may look to government (local and national) to provide risk mitigation solutions to reduce their premiums.

    The other problem linked to affordability is underinsurance, where the insurance payout from a total loss claim will not cover policyholder costs. As insurance costs increase, policyholders may look to reduce their premiums, choosing higher excesses or lower sum insured values. This latter option may result in a policyholder being underinsured. It can create bad publicity for insurers, or even result in regulatory fines if the insurer is found not to have explained the risks to a policyholder of reducing their sum insured.

    How are community expectations aligning with insurer or government actions?

    Aotearoa has high levels of insurance coverage, especially for home insurance. As premiums continue to rise, it’s likely the number of homeowners who are underinsured (or those with no insurance) will increase. Following large natural disasters, people expect government to provide support in addition to the insurance industry, based on recent buy-back schemes from the Auckland floods and Cyclone Gabrielle. This approach is unsustainable long term, and industry bodies such as the ICNZ are encouraging more investment in resilience measures, rather than the post-event support we’ve seen lately. The recent resilience boost to Northland’s most flood-prone marae, which is almost fully government funded, is a good example of these measures. The industry understands resilience isn’t a simple one-size-fits all solution – rather, it requires careful planning and an individualised approach.

    Where are the gaps in reducing risk from an insurer perspective?

    The insurance industry would like greater understanding of underlying risks properties face. These are captured by Land Information Memorandums (LIMs) when properties are bought or when new builds are consented. While knowing the risks will help potential buyers, some homeowners are pushing back on this information being included fearing attempts to map areas most at risk may reduce property values. This is the crux of the issue.

    The industry also wants more involvement in the consenting-to-build process, to stop housing construction in known bad-risk areas.

    Insurers already understand the risks properties face, so whether or not the information is on a LIM, the cost of insurance for high-risk properties is likely to keep increasing. As premiums become less affordable, property values will be affected, as banks require mortgages to be backed by insurance.

    The industry also wants more involvement in the consenting-to-build process, to stop housing construction in known bad-risk areas. Currently, insurers are not involved and the insurability of a property is only considered once the property has been built.

    How is the government addressing insurance affordability?

    Pooled insurance, such as the EQC cover, is designed to keep insurance affordable. In the case of the EQC, this is done by not risk rating for earthquake risk. The EQC premium for a $300K home in Auckland is the same as a $300K home in Wellington. But EQC doesn’t provide coverage for damage to a home due to a flood and given pooled insurance doesn’t reduce the risk of a house flooding, it’s only part of the answer.

    The government has also committed $200 million in the 2024 budget which, combined with co-investment from local governments, will accelerate the implementation of 42 flood-resilience projects.

    Are there any approaches to insurance affordability in the pipeline?

    Large-scale improvements will take time, with small incremental changes being implemented now. Given the scale of the problem, it’s important to recognise significant change can only occur if all parties work together. For example, if insurers provide their insights into existing risks, the government can then identify the most effective resilience investments, which will help improve insurance affordability.

    Does experience overseas shed any light on possible actions to take or not to take?

    In Australia, the government introduced the Cyclone Reinsurance Pool in 2022, which aims to improve insurance affordability in northern Australia. This partly works due to the nature of cyclone risks in Australia, which tend to impact the northern areas. In this regard, the Cyclone Reinsurance Pool could be considered as similar in design to the EQC in NZ.

    Given the scale of the problem, it’s important to recognise significant change can only occur if all parties work together.

    In the UK, Flood Re was established in 2016 to make flood insurance more affordable. The scheme excludes homes built after 2009 to avoid promoting development of homes in high-risk areas. In 2022, the scheme introduced its Build Back Better initiative, encouraging risk mitigation for individual properties. This initiative offers householders the chance to install property flood resilience measures up to the value of £10,000 (about NZD$20,000) when repairing their properties after a flood.

    At this critical time for the planet, where does climate change fit into the story of rising premiums and profits and the outlook for the industry?

    We’re likely to see more weather events, with greater intensity and extremes. Areas not previously considered at risk may slowly become more exposed. This could lead to managed retreat, which has been identified as a climate change adaptation option in the government’s National Adaptation Plan, with insurance potentially the driver for the decision to retreat.

    Managed retreat is where an insurer pays out the full sum insured (only if the property has had a significant claim), which the policyholder then uses to buy or build in a better location. This means insurers will stop writing higher-risk properties, which should improve their claims performance in the long term. For other high-risk properties without a previous claim, the insurer would look to stop providing insurance, reducing the value of the property and leaving the homeowner out of pocket. The question of who pays for this loss remains unclear.

    What more can insurers do to ensure industry sustainability and provide value to policyholders?

    Insurers have absorbed major losses over the past 20 years and they’ll continue to provide protection to Aotearoa homeowners. But they’ll also need to balance their internal risks, with the amount of insurance they provide limited by their capital levels and reinsurance protection. For highly exposed areas, such as Wellington with its earthquake risk, they’ll be able to offer cover only up to specified levels.

    More broadly, insurers have an opportunity to contribute by sharing their deep understanding of risk. These valuable insights inform their pricing but could also help government identify the most cost-effective approach to risk protection, whether through mitigation, managed retreat or other solutions.

    With all players coming together – insurers, government and local communities – making informed decisions that consider the safety of Aotearoa properties, the insurance industry will continue to strengthen and protect people into the future.

  • What climate disclosure means for the public sector

    The Australian Government recently announced it will be phasing in climate reporting requirements for Commonwealth entities. Alan Greenfield and Sarah Wood provide a summary of what’s happening at the Commonwealth level, and an update on what’s changing for states and territories.

    As the private sector firmly focuses on navigating new climate-disclosure laws, government entities too are working out how they’ll be publicly reporting their own financial risks and opportunities related to climate. We look at what’s in store across the Australian public sector.

    Commonwealth

    The Australian Government has committed to mandatory public disclosures for Commonwealth entities and companies (which includes Commonwealth departments).

    Why introduce public sector climate-risk reporting?

    The aims for Commonwealth public sector disclosure are to:

    • Help these organisations prepare for and respond to the changing climate
    • Support the delivery of Australia’s emissions reductions targets under the Paris Agreement and the Government’s APS Net Zero by 2030 target
    • Provide greater transparency, accountability and credibility in the way climate risks are managed across the Commonwealth public sector.

    In December 2023, the Commonwealth Department of Finance confirmed the content and phasing of climate disclosures for Commonwealth entities. Here’s a summary of the key features of the disclosure regime …

    Among the aims for public sector climate reporting is greater transparency and accountability

    Which entities and companies will be required to make disclosures?

    All Commonwealth entities and Commonwealth companies will be required to make climate disclosures in their annual reports.

    What will entities and companies need to disclose?

    If Commonwealth companies meet the size thresholds for inclusion in the corporate sector disclosure regime (which we covered recently), they’ll be required to disclose under the corporate regime. The Department of Finance has estimated there are at least five Commonwealth companies that meet these thresholds at the moment.

    For everyone else, Commonwealth Climate Disclosures will apply. These are being developed by the Department of Finance and expected to be finalised in Q2 2024. In brief, they’ll:

    • Be tailored according to what type of Commonwealth entity the organisation is – non-corporate Commonwealth entity, corporate Commonwealth entity or Commonwealth company
    • Align with the requirements for the private sector, but will be specifically tailored to account for the differences in structure, objectives and functions of Commonwealth entities and companies, as well as the regulatory environments they operate under and how they interact with other government policies.

    When will disclosures need to be made?

    Similar to the private sector, disclosure requirements will be phased across four tranches. The first phase is a pilot and will be for FY 2023/24, applying to all departments of state. As standards aren’t yet finalised, these entities will use pilot requirements to complete their disclosures.

    From FY 2024/25 onwards, remaining entities will be phased over three years, according to entity type, size and profile. Large entities, those entities with responsibility for climate change policy, and high-emitting entities are the first cabs off the rank. More detail can be found on the Department of Finance’s website.

    States and territories

    While the Commonwealth is now the most advanced jurisdiction in Australia when it comes to mandating disclosures, the states and territories have undertaken several years of work on this. In 2022, the Board of Treasurers – the treasurers of the six states and two territories – agreed that all Australian jurisdictions would release a regular climate-related financial disclosure statement on a whole-of-government basis. This would be informed by the Taskforce on Climate-related Financial Disclosures (TCFD), that is, the precursor to the ISSB IFRS S2. The content and commencement date of their respective whole-of-government disclosure would be determined by each jurisdiction.

    So where is each state or territory up to in producing a whole-of-government climate disclosure statement? Here’s a brief rundown, including whether they’ve announced mandatory disclosures at an entity level …

    Victoria

    State of play – In 2022, the Victorian Government produced a whole-of-government Climate-related Risk Disclosure Statement, marking the first time in Australia a government had disclosed in line with the TCFD recommendations. The primary purpose is to outline how the Victorian Government is:

    • Managing climate-related risks to the state of Victoria, and to the Government’s delivery of services to the community
    • Seizing the opportunities associated with the transition to a net-zero, climate-resilient economy.

    While the Commonwealth is now the most advanced jurisdiction in Australia when it comes to mandating disclosures, the states and territories have undertaken several years of work on this.

    On an individual entity level, departments and administrative offices must disclose a description of the entity’s approach to understanding and managing climate-related risks and opportunities relating to its assets, operations and service delivery, and (where possible) a description of its planned responses. The statement should be modelled against the recommended pillars of the TCFD (Governance, Strategy, Risk Management, and Metrics and Targets).

    Next steps – Victoria’s future work program for climate risk includes:

    • Increasing the evidence base for climate action to develop policy responses and harness Victoria’s climate-related opportunities
    • Using climate scenario analysis
    • Strengthening the understanding and assessment of the impact of climate change on the Victorian economy and on the financial performance and position of the state
    • Bolstering enterprise risk management frameworks to ensure climate-related risks are effectively identified, assessed and managed through departments.

    New South Wales

    State of play – In 2021, the NSW Government announced it would be conducting a climate disclosure statement pilot on three public sector organisations – Essential Energy, the Environment Protection Authority, and the National Parks and Wildlife Service. The disclosures were published in late 2022 and align with the TCFD framework.

    Next steps – In November 2022, the NSW Government said learnings from the pilot would be used to:

    • Produce a guide to support government entities intending to make climate-related disclosures in future
    • Help the NSW Government develop a whole-of-government climate-change disclosure.

    In December 2022, The NSW Government’s Net Zero Plan Implementation Update 2022 committed all NSW agencies to identify their own climate change risks by the end of 2023.

    Queensland

    State of play – In June 2023, Queensland Treasury provided an update to Queensland agencies where it noted sustainability reporting for the Queensland public sector is still under development and will be whole-of-government led. For the 2022/23 reporting period, it told agencies they should not apply draft ISSB standards or the TCFD framework.

    Next steps – Queensland Treasury will provide further information on how the ISSB standards will apply to agencies in future reporting periods.

    Western Australia

    State of play – Similarly to Queensland, the Western Australian Office of the Auditor General (OAG), in December 2023, noted several Western Australian government entities (mainly government trading enterprises) had started to consider and disclose climate-related financial risks. In its annual report, the OAG commended entities’ efforts towards providing climate-related disclosures and commentary. But it noted that in the absence of specific standards and templates, entities should use caution before making any disclosures. It also reminded entities that disclosures must be adequately substantiated.

    Next steps – The Western Australian Parliament, government and central agencies are determining what level of reporting requirements would apply to public sector entities in Western Australia, based on what is proposed and enacted nationally, and will update the financial framework accordingly.

    We expect to see more announcements from states and territories this year, as they work out further details and as the momentum continues to build internationally towards standardised, mandatory climate disclosures.

  • Mandatory climate disclosures – what’s new for insurers

    In 2023, mandatory climate disclosures were a major talking point for Australia’s business community, as the Australian Government announced plans to implement new reporting rules. With the New Year barely underway, Treasury released its final position paper last week on mandatory climate-related financial disclosures. What does this mean for insurers? We answer all your burning questions.

    Insurers can expect some of the most important details for mandatory disclosures will be fleshed out during 2024, starting with this final position paper from Treasury. Issues considered within its pages include which companies disclosures will apply to, and the readiness of the audit and assurance community to achieve this step-change in reporting requirements. Here are the crucial points insurers will need to consider as they begin or ramp up their climate disclosure journey.

    In 2024, insurers can expect some of the most crucial details of mandatory disclosures to be decided

    What are the key takeaways from the final policy?

    • Standards will align with the International Sustainability Standards Board’s (ISSB) inaugural IFRS S2 standard, finalised in June 2023. IFRS S2 provides a common international language for disclosing the effects of climate-related risks and opportunities on a company’s prospects. The Australian Accounting Standards Board is currently consulting on modifications to these standards for Australian matters and requirements.
    • Disclosures will apply for large businesses and be phased in three groups – starting with the largest companies.
    • The smaller of the large businesses won’t automatically have to disclose, rather they’ll need to make a judgment as to whether they face material climate risks or opportunities. This reflects feedback from stakeholders about unnecessary regulatory burden.
    • Full assurance requirements aren’t applicable until 2030. This will allow the auditing and assurance profession time to adjust via the phases to a whole new area of assurance.

    Timeline – How did we get here?

    2017

    Since the release of the Taskforce on Climate-related Financial Disclosures (TCFD) report in 2017, there has been a global trend towards large businesses voluntarily (and later for some jurisdictions, mandatorily) disclosing climate-related financial information.

    2022

    In December 2022, the Australian Government committed to introducing standardised, internationally aligned reporting requirements for Australian businesses to make climate risk and opportunity disclosures.

    2023

    Last year was critical in giving effect to Australia’s commitment, with two rounds of consultation on the specific design of the reporting requirements, their implementation and sequencing. We discussed the detail of the policy design last year in our articles Climate change: key considerations for general insurers and New mandatory climate disclosures – what small to medium insurers need to know. The second consultation paper, released in June 2023, received more than 146 responses from interested parties.

    2023 was also a big year internationally, with the ISSB stating its IFRS S2 standard was ‘ushering in a new era of sustainability-related disclosures’.

    2024

    Which brings us to last week, when the Treasury released its final policy position – reflecting feedback from the earlier rounds of consultation.

    What needs to be reported?

    Reporting content hasn’t changed since the second consultation paper. Climate-related financial disclosures will include information about an entity’s climate-related risks and opportunities, as required by Australian climate disclosure standards, including:

    • Information relating to governance, strategy, risk management, and metrics and targets (including Scope 1* and Scope 2* greenhouse gas emissions). These will be required from the first year of reporting.
    • Scope 3* emissions (i.e. emissions that occur up or down an organisation’s supply chain and emissions associated with their financing or investment activities). These will be required from the second year of reporting. Scope 3 disclosures would represent information available at the reporting date without undue cost or effort.

    The Government endorses full adoption of the ISSB IFRS S2 Climate-related Disclosures standard. Modifications from IFRS S2 are limited to those necessary to ensure standards are fit for purpose for Australia (e.g. Australia’s greenhouse gas emissions estimation methodologies and international climate change commitments).

    Will mandatory disclosures apply to my organisation?

    This is a critical change, and the answer now is: not necessarily for smaller insurers.

    To check whether mandatory disclosures apply, entities must be required to prepare and lodge annual reports under Chapter 2M of the Corporations Act and fall within one (or more) of the following three categories:

    Insurers will fall into one of three groups, in assessing whether mandatory disclosures apply

    Organisations (including smaller insurers) captured under Group 3 are required to make climate-related financial disclosures in line with the climate disclosure standards only if they face material climate-related risks or opportunities for the financial reporting period. Where Group 3 entities assess they don’t have material risks or opportunities, they would be required only to disclose a statement to that effect.

    This is a critical change from what was proposed last year (i.e. that all Group 3 entities would be required to make mandatory disclosures), and is in response to feedback that the regulatory burden would be excessive compared to the benefit from their inclusion.

    It’s important for insurers to note that even if they assess their organisation to be exempt (either because they don’t meet the materiality threshold for Group 3 entities, or they’re smaller in size than a Group 3 entity), they still need to consider APRA’s Prudential Practice Guide CPG 229 Climate Change Financial Risks.

    When do mandatory disclosures take effect?

    As we outline in the table above, entities subject to mandatory climate-related financial disclosure will be phased in three groups over a four-year period. The Government is asking for stakeholder feedback on whether amending legislation to require a 1 January 2025 commencement date for Group 1 entities would improve the quality of reporting during the transition year.

    Where do I make disclosures?

    Climate-related financial disclosures will sit within a sustainability report forming the fourth report required as part of financial reporting obligations in an entity’s annual report. Entities should include an index table within their annual report that enables users to easily navigate the climate disclosures. Timing of annual report lodgement, including for those required to lodge with ASIC, will stay consistent with current requirements under section 319 of the Corporations Act.

    Entities are required to make their sustainability disclosure reports publicly available on their website the day after the report is lodged with ASIC.

    Will my disclosures need to be audited?

    Yes, in a similar way to disclosures currently required under the Corporations Act for financial reports. Entities will need to obtain an assurance report from their financial auditors, who’ll use technical climate and sustainability experts where required. These requirements will eventually be set out in Australian assurance standards for climate disclosures.

    Importantly, the Government has intentionally not mandated a roadmap for the phasing in and scaling up of assurance requirements for climate disclosures, due to the:

    • Capability uplift required in the assurance and audit industry
    • Uncertainty in determining how long this could take
    • Development of an international standard on sustainability assurance, which is underway but not expected to be finalised until the end of 2024.

    Limited assurance of Scope 1 and Scope 2 emissions is required, scaling up to the reasonable assurance of climate-related financial disclosures by 2030. The roadmap to reasonable assurance will be flexibly determined by the Auditing and Assurance Standards Board (AUASB).

    What else do I need to know?

    Entities will be required to disclose against well-established and understood industry-based metrics only from 1 July 2030. They can choose to disclose relevant industry-based metrics voluntarily prior to this date. Interested insurers should actively engage in the Insurance Council of Australia’s climate change program of work to keep up to date with insurance-industry-specific metric discussions.

    There is also liability relief for disclosures relating to Scope 3 emissions and certain climate-related forward-looking statements for a fixed three-year period. For reports issued between 1 July 2015 and 30 June 2018, only the regulator will be able to bring action relating to breaches of relevant provisions, and the remedies available to the regulator are limited to injunctions and declarations.

    What are my first steps?

    Insurers should make an initial assessment as to which reporting group (1, 2, 3 or N/A) they’re likely to belong by the end of the relevant financial reporting period. This will help determine whether you should automatically start preparing for mandatory disclosure or need to assess whether or not you face material climate-related risks or opportunities.

    *As a refresher, Scope 1 are direct GHG emissions that occur from sources that are owned or controlled by the company (e.g. emissions from combustion in owned or controlled vehicles). Scope 2 are emissions from the generation of purchased electricity consumed by the company, and Scope 3 are all other indirect emissions.

  • Living life to the full – Dan’s on a role

    Living life to the full – Dan’s on a role

    From moving countries to swapping a public sector career for private consulting – all while juggling four kids, a sporty lifestyle and numerous pets – Daniel Stoner was never afraid to challenge his limits. As he begins his newest chapter, as Principal at Taylor Fry, Dan shares his career journey, passions and aspirations.

    Did you always want to be an actuary? What do you enjoy most about the work you do?

    It wasn’t an ambition I had when I was young, but I was good at maths. This led to a Mathematics degree and the actuarial profession seemed like a good opportunity to use my maths skills. Early on in my career, experiences at a consulting firm and a corporate bank helped me realise I’m most passionate about community-oriented work that delivers social value.

    I sought work in the social sector and moved from Auckland to Wellington to join the Ministry of Social Development (MSD). Although it’s not a traditional actuarial area, our skills for forecasting and having a risk mindset have clear applications to social sector issues because these are long term in nature, and often intergenerational.

    Bring it on: Dan goes with the flow, dividing his time between work, family and the great outdoors

    At MSD, I worked once a week at a Work and Income office, which is New Zealand’s equivalent to Centrelink. That gave me invaluable frontline perspective on who’s most impacted by the work I do. Although we’re not the ones applying interventions directly, my work informs system-level factors that can have a significant impact on people’s lives – and this is really motivating for me.

    Why did you decide to join Taylor Fry?

    Taylor Fry has had a long-standing partnership with the New Zealand government and specifically MSD, modelling people’s long-term social outcomes. While at MSD, I worked closely with the Taylor Fry team on how best to translate their modelling results into insights that best informed the policy and operational settings for the ministry. It was clear we shared similar values – they were so down to earth and genuine. They were also technically excellent, and I was excited by the opportunity to join them.

    The prospect of leading such a strong team is exciting  … to make a worthy difference together across a variety of social issues here in New Zealand.

    What does this new role mean for you?

    What’s most important for me is to be able to continue doing good work that has a positive impact and means something for others. At the same time, the prospect of leading such a strong team is exciting – supporting their professional development as social sector actuaries to make a worthy difference together across a variety of social issues here in New Zealand. We have a great opportunity, especially with the new government, to offer our unique capabilities and facilitate effective social investment.

    How does your life play out away from work?

    My hands are full! My wife and I have four children, and about 30 pets, including chickens, cats, dogs and fish. I enjoy supporting the kids’ interests, particularly sports – having been an avid triathlete and footballer when I was younger. I coach junior sports teams, and volunteer for sporting club committees and my kids’ school board. If I have any spare time, you’ll find me on my bike or out for a run soaking in the spectacular natural New Zealand landscape – so soothing for the soul!

    Learn more about Dan’s work in the social sector

  • How inflation is changing the insurer landscape

    We look beyond the headline numbers to assess where the current inflationary pressures are being felt most, the outlook for FY24 and what insurers can do to thrive over the next few years.

    Our analysis shows we’re past the inflationary peak for most sectors, but inflation continues to remain above long-term average levels and will increase claims cost pressures for insurers. Indeed, in its recent report on the Australian economy, the International Monetary Fund said headline inflation’s “decline is slow and core inflation remains sticky”. At a minimum, insurers will need to have a deep understanding of the drivers of inflation for each loss type and the flow-on impact on claims costs and premiums.
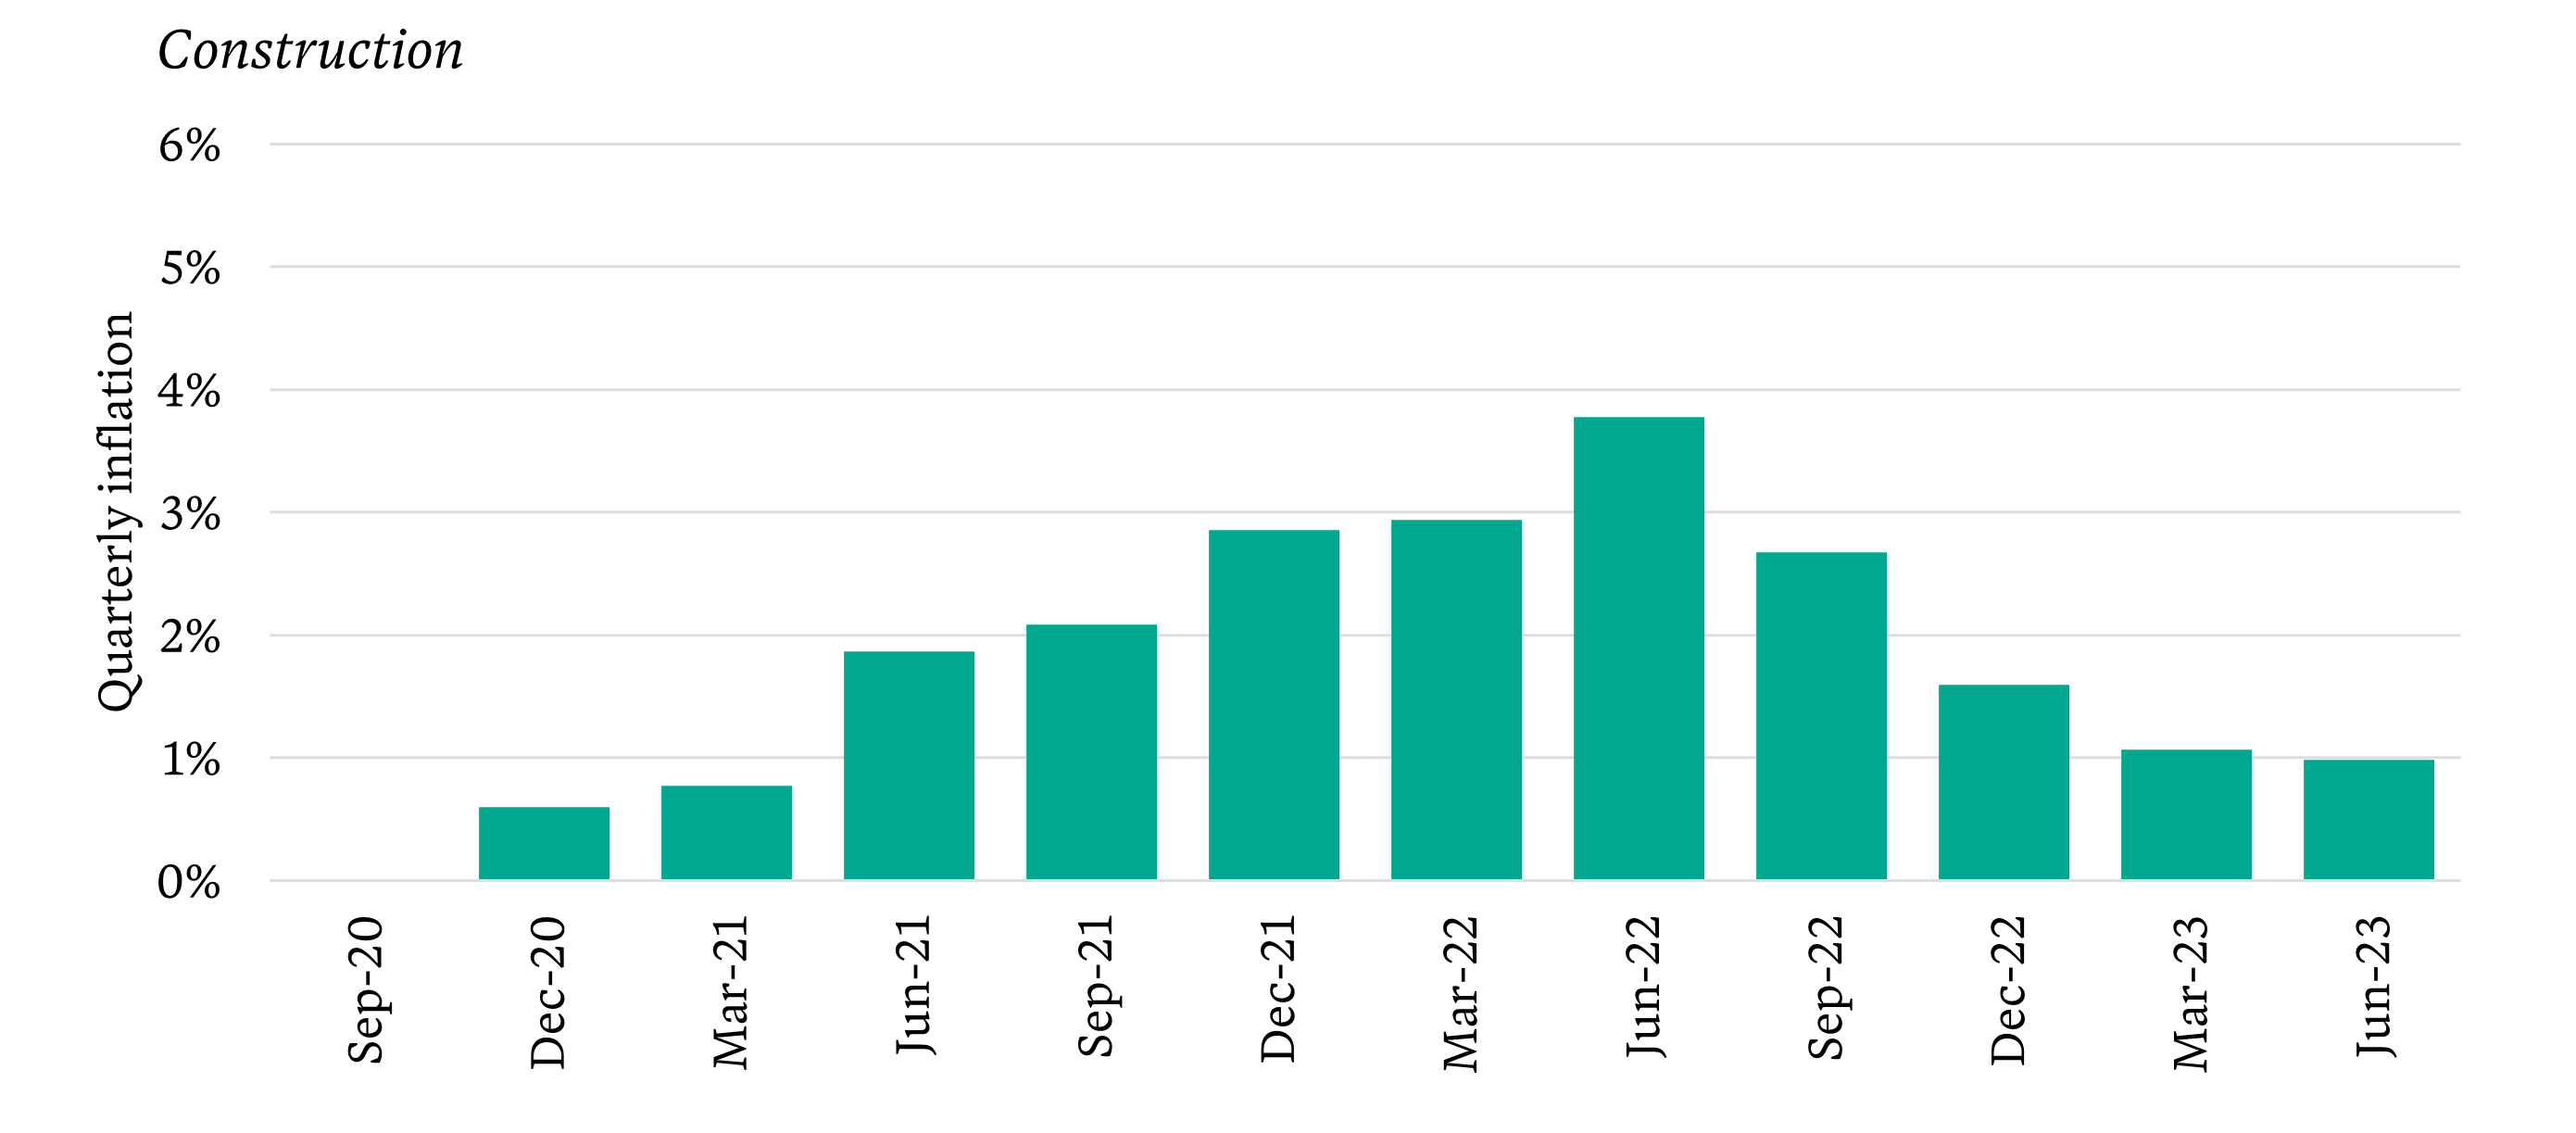
    Construction, motor parts and travel are key drivers of claims cost inflation for property, motor and travel insurers. We summarise the Australian Bureau of Statistics quarterly inflation figures for the three areas to help us capture the impacts on insurers.

    With claims costs increasing, insurers will need to understand inflationary drivers and impacts

    Key driver 1 – Construction

    Over the two years to 30 June 2023, construction costs have increased by 20%. Cost pressures have been driven by an increase in demand for materials combined with supply constraints and increases in energy and freight costs. The good news is that the past two quarters show construction cost increases are slowing. We expect material cost pressures will reduce over FY24, as supply chain pressures reduce and demand weakens.
    Of course, the cost of construction is only one of the factors contributing to claims costs and premiums. Unfortunately for homeowners, the increasing frequency and cost of catastrophes and increases in reinsurance costs continue to drive up premiums, despite the weakening inflationary pressures on construction costs. IAG increased home insurance premiums by 20% from February 2023.
    In its recent thought leadership report, Home Insurance Affordability Update, the Actuaries Institute states 12% of households are now affordability stressed, paying more than four weeks’ gross income towards home insurance premiums. Various initiatives and measures to mitigate these risks have been proposed but will take time. Meanwhile, affordability stresses will further increase as the risks continue to rise and insurers are flagging additional premium increases.

    Construction cost increases are slowing, but catastrophes continue to drive up premiums

    Key driver 2 – Motor spare parts

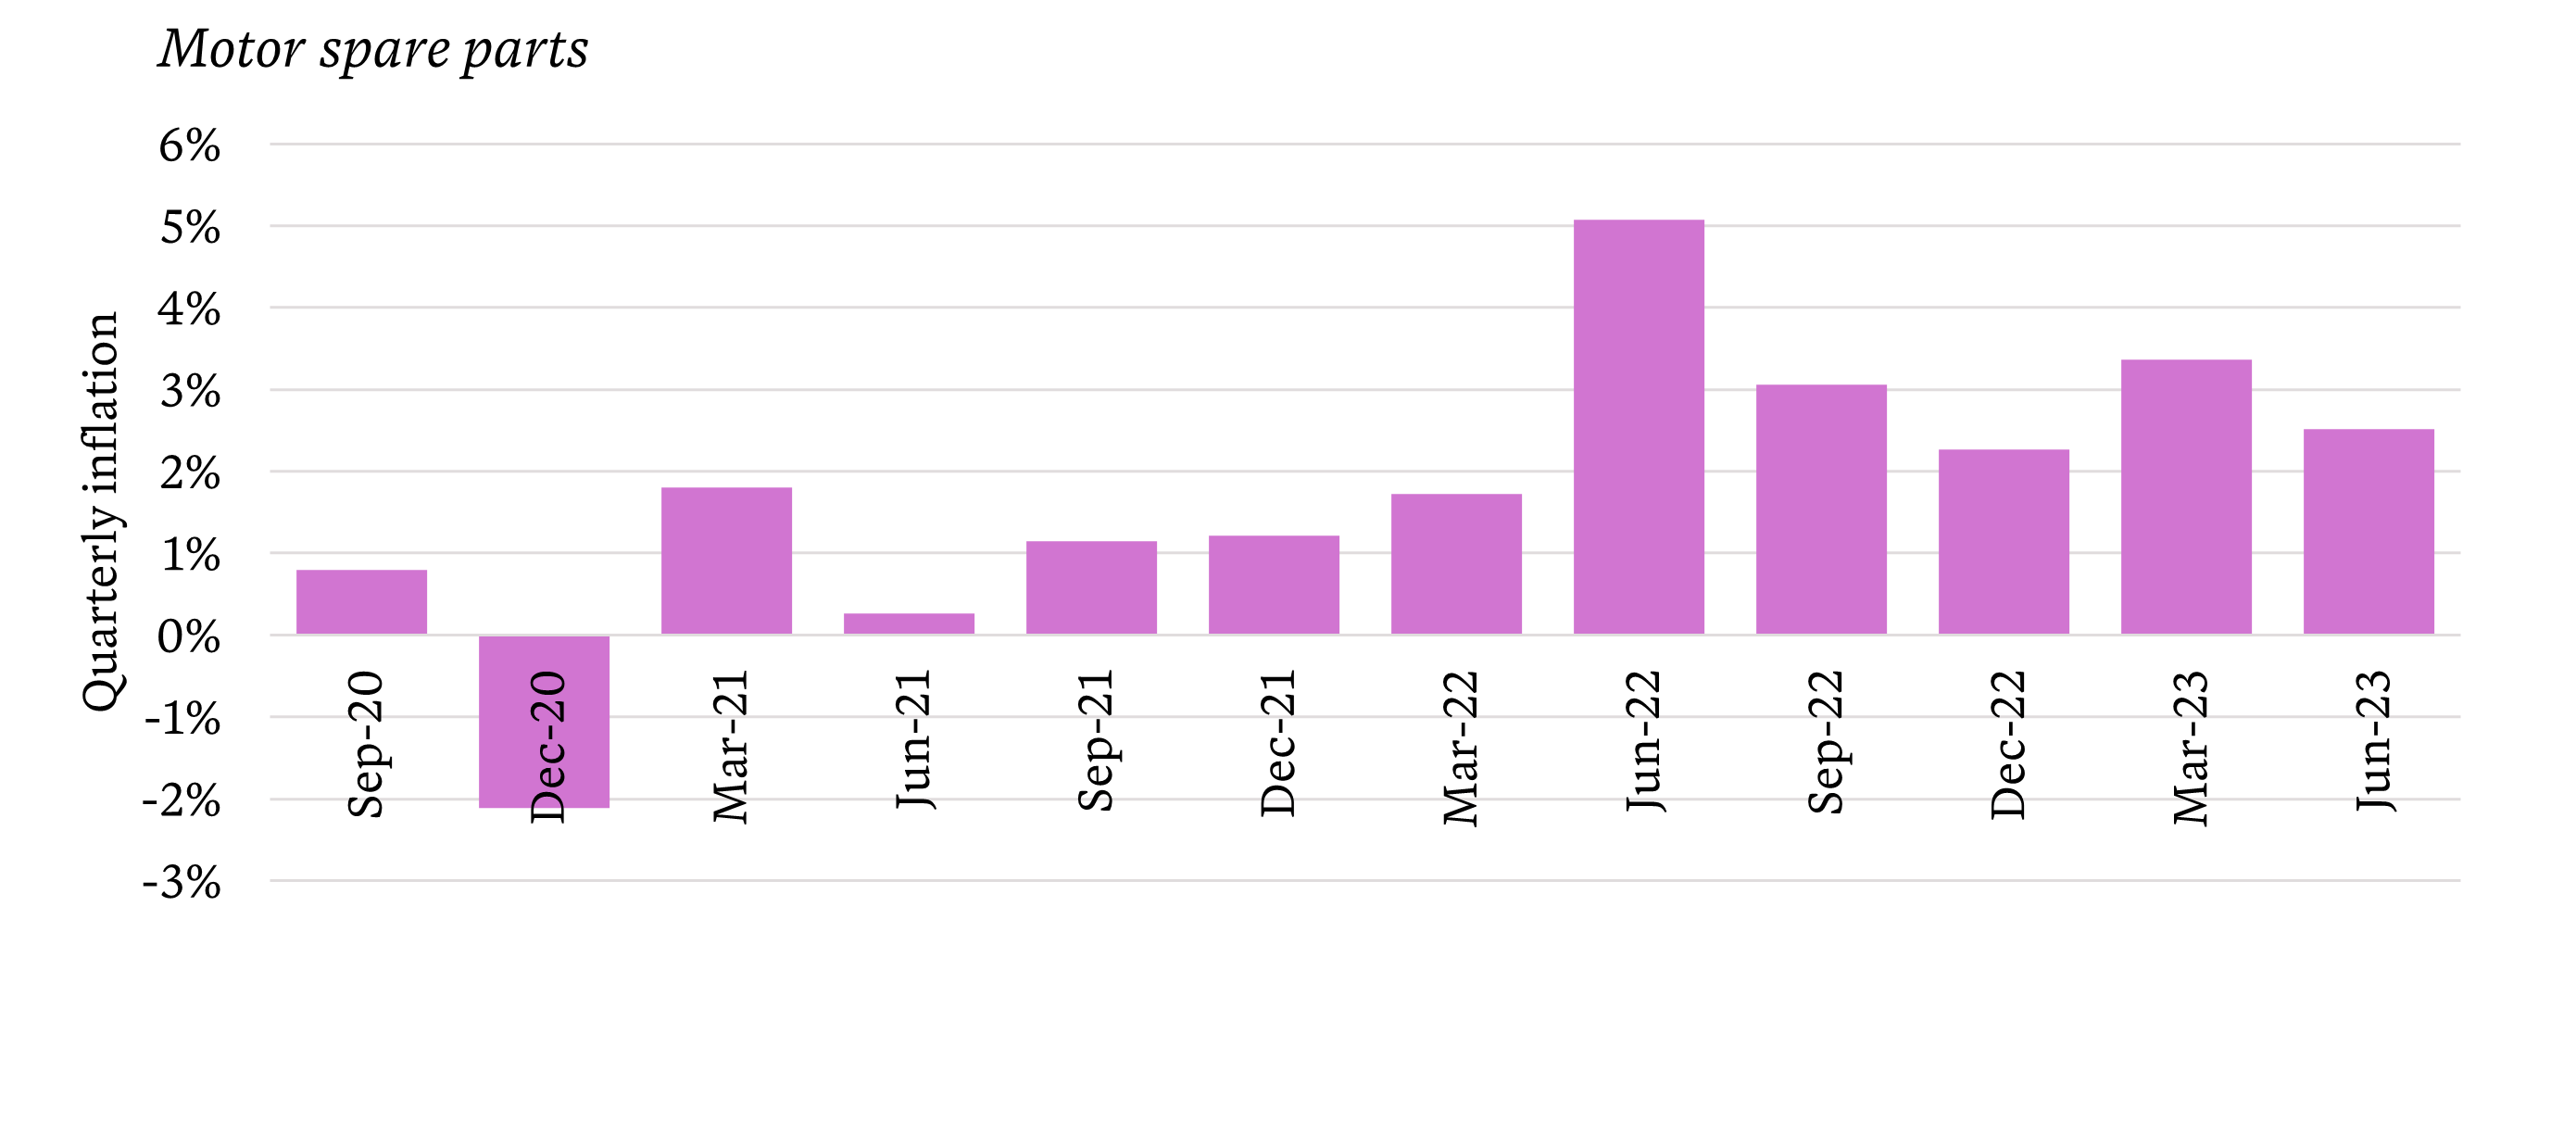
    Motor parts costs have increased by 23% in the past two years. Supply chain constraints and labour shortages are mainly behind increases in claims costs for insurers. Advancement in technology used in vehicle components is another key contributor. In particular, components that are most likely to be damaged in a collision such as headlights and windscreens have seen sharp price increases due to technological advancement in modern vehicles, including advanced driver-assistance systems and smart sensors.
    The increase in motor parts costs has impacted motor insurance premiums over the past few years. Reflecting this experience, APRA’s latest general insurance statistics show a 14% increase in average premiums over FY23 for the industry.
    We expect motor vehicle cost pressures to remain elevated in FY24. The main pressures over the next year come from labour shortages in the motor repair industry and the supply of spare parts, which will have an impact on repair times and costs.

    APRA reports a 14% increase in average motor premiums and we expect cost pressures to remain

    Key driver 3 – Holiday travel and accommodation

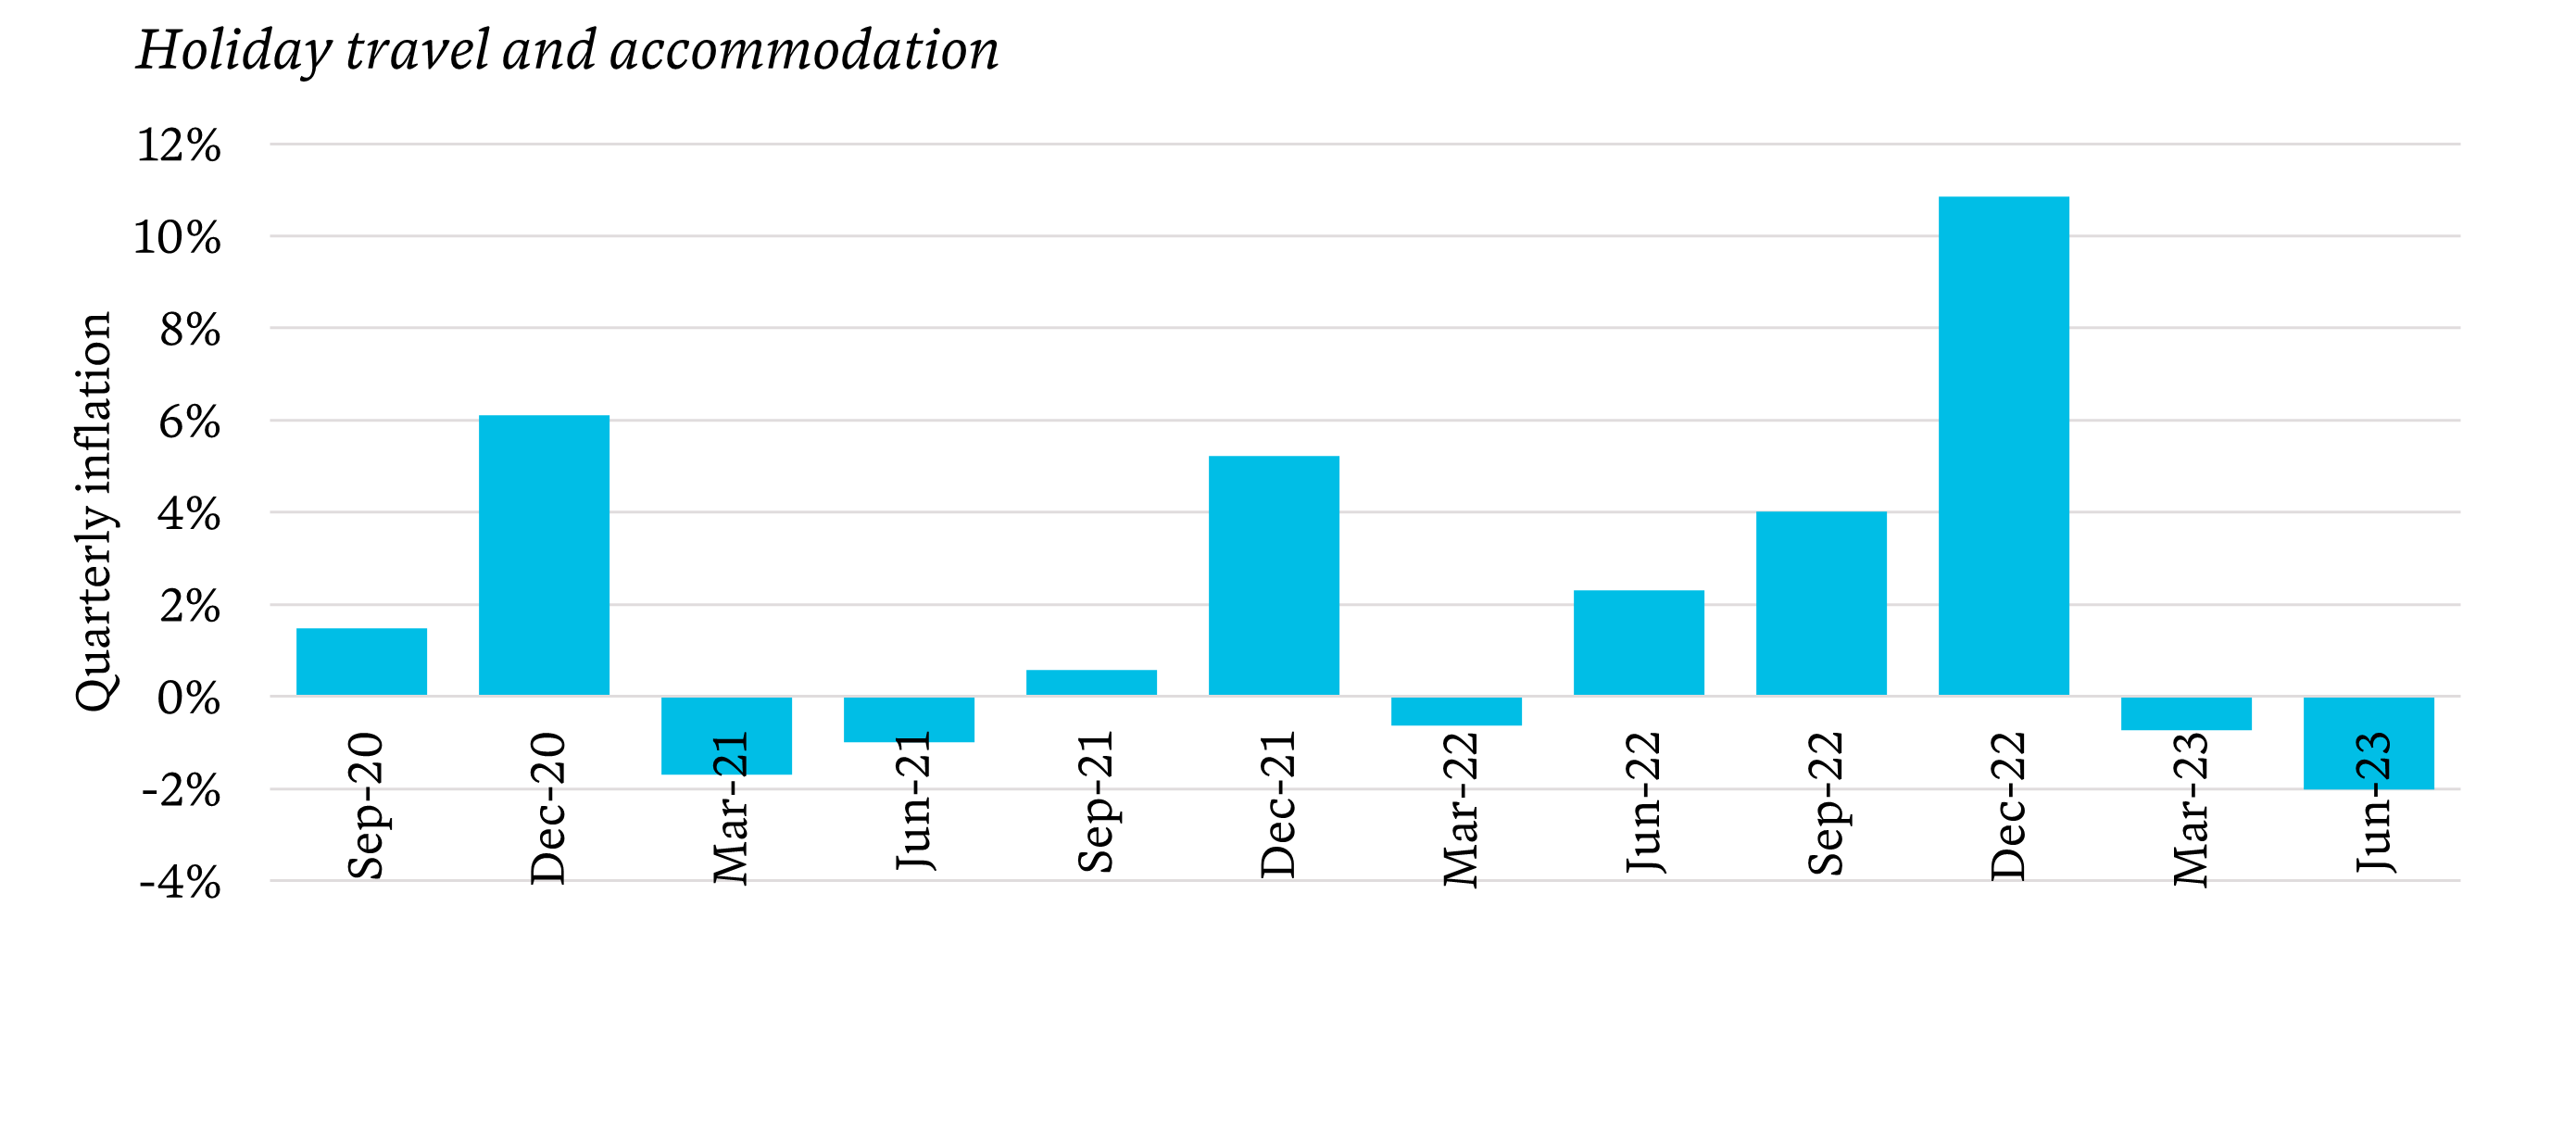
    In good news for travellers, the cost of travel and accommodation reduced by 3% in the six months to June 2023, following record high prices last summer. The price increases in the past two years are due to a combination of increased demand post COVID-19, the cost of aviation fuel and reduced supply of air travel.
    The outlook is for prices to reduce further as supply comes back online. Travel insurers will need to watch this space closely and adjust premiums to remain competitive.

    Prices for travellers should further reduce from earlier record highs, as supply comes back online

    Top 4 insurer actions – What it will take to thrive

    In addition to closely monitoring claims costs and adjusting premiums, there are several actions insurers can take to thrive in this environment:

    1. Focus on customer retention strategies, given substantial price increases – Price is not the only factor that determines whether a customer renews. Improving customer experience – at the time of acquiring a policy or receiving a claim and when responding to a customer enquiry – is now more important than ever. For example, claim settlement times are being slashed with the industry investing in technology and artificial intelligence to help reduce the time it takes to assess a claim from weeks to minutes. The standout in this space is Lemonade Insurance, setting a new record of paying a claim in under two seconds.
    2. Be alert to an increase in the number of vulnerable customers and review your financial hardship policies – Vulnerability is broad and can be situational. It’s important your customer service team is on high alert and can spot the signs.
    3. Consider the potential for increased fraud/claim exaggeration activity, as ongoing cost pressures hit home for consumers and businesses – In 2017, the Insurance Council of Australia reported insurers detected $280 million in fraudulent claims across personal lines classes. The true cost of fraudulent claims will be multiples higher than this and can be expected to increase in times of economic stress. The industry is investing in AI to detect fraud and flag claims for additional review. Provided these solutions are applied correctly, this is a positive development for consumers.
    4. Closely monitor customer churn, with a focus on retaining your most profitable customers – Large premium rate increases are associated with an increase in churn, as customers search for a better deal. In this environment, it’s increasingly important for insurers to understand profitability at a customer level and focus efforts on retaining customers who have a high lifetime value. Insurers that have a comprehensive understanding of individual risks and provide a great customer experience, as we outlined in Action 1., will be best placed to weather the storm.
  • RADAR FY2023 New Zealand Snapshot

    Affordability and a shifting regulatory environment – including upcoming ESG obligations – are dominating industry experience across the nation. In RADAR FY2023 New Zealand Snapshot, we use the latest data and our market expertise to shed light on the New Zealand general insurance landscape and help insurers chart a steady path forward.


    Download our report
    to understand the latest developments and understand what it all means for insurers

    The NZ general insurance industry is facing a raft of change on various fronts, with natural disasters once again the leading concern. This time, they’ve struck on a scale never before seen in Aotearoa, accelerating discussion around managed retreat from high-risk locations and frameworks to address the issues.

    At the same time, the Reserve Bank and the Financial Markets Authority are firmly focused on ensuring regulatory settings respond appropriately to a rapidly evolving marketplace.

    More proactive and intensive supervision of insurers is likely, while fair conduct, customer expectations and cyber reporting are all high on the agenda.

    Our report also highlights the wave of upcoming standardised Environmental, Social and Governance (ESG) reporting disclosures – the biggest changes to financial reporting and disclosure standards in a generation – as well as a host of other ESG obligations on the horizon.

    RADAR New Zealand FY2023 Snapshot offers critical insurance insights, exploring all the important details, considerations and actions for insurers in building resilience and sustainability for Aotearoa in 2024 and beyond.

  • Workers compensation and our ageing workforce

    Australians are expected to live longer than ever before and in better health, which means many of us will work for more years and retire later. What are the impacts for workers compensation? We explore the unique challenges and opportunities for governments and society posed by our ageing workforce.

    Over the next 40 years, the number of people aged over 65 is expected to double, while the number of people aged over 85 is expected to triple, according to the Australian Government’s latest  intergenerational report.

    People over 65 are more likely to prefer working part time and may seek less physical jobs

    Not only are Australians expected to live longer, but they’re also expected to spend more years in good health. With better health and longer life expectancy, many Australians will spend more years working and retiring later. There are several reasons for this, including:

    • Sharp and ongoing increases in cost of living
    • To help stay mentally and physically active
    • To accumulate higher savings for when physical work is no longer possible, which may contribute to maintaining standards of living in retirement
    • To help provide financial support to family for longer.

    Analysis conducted by the Australian Institute for Health and Welfare suggests that increased workforce participation is already happening for older people. Average workforce participation for over-65s  has increased from 10.6% in 2010 to 14.8% in 2021. This has been observed for males and females.

    Research published by Macquarie Business School, has recommended further increases to the age pension eligibility age, from the current legislated amount of 67 years up to 70 years by 2050. While the government has not yet announced any intention to further increase the age pension age, it’s no doubt a useful lever for it to manage the costs of a larger Australia (about 40 million by 2062) and an older population.

    With people expected to live and work for longer, we’re likely to see a continuing ageing of the Australian workforce. This will bring some unique challenges for workers compensation systems.

    Older workers – Needs vs risks

    As workers age, the type of work the choose to do also changes. For example, people aged over 65 are more likely to prefer working part time than full time. Similarly, older workers may shift from more physically intensive jobs towards desk  . It’s important for schemes and employers to understand changes in the mix of their employees over time and how that could impact employee exposure to injury and ability to return to work.

    Understanding claimant patterns

    Analysis published by Workcover WA indicates that workers aged over 55 are 50% more likely to lodge a workers compensation claim than workers aged 15-34. There may be several reasons for this, including:

    • Older people can be more susceptible to injuries, particularly slips and trips and bodily stress, as a higher proportion of older workers suffer from chronic health conditions
    • Experienced workers may be less worried about burning bridges with their employer by making a claim.

    Separate analysis published by SafeWork Australia in 2015, states that workers over 40 are more likely to be compensated for a work-related mental injury condition than workers under 40. This has been observed for both males and females, as the chart shows below.

    Older workers are more likely to claim for different types of injuries, including psychological

    While the frequency of serious mental disorder claims seems to be highest for middle-aged workers (40-59 years), the frequency for older workers (over 60 years) is notably higher than the frequency for younger workers (24 years and under). SafeWork Australia further notes that older workers (over 55 years) had a 128% higher chance of being awarded a mental disorder claim as a result of work pressure compared to workers aged 24 years and under.

    A unique risk profile

    These analyses indicate that older workers have a unique risk profile and are more likely to claim for different types of injuries (across both physical and psychological injuries), compared to younger workers. A shift towards an older working population will therefore likely result in a change in the frequency and mix of types of injuries.

    Publicly available research from other schemes is limited, however it’s likely that other schemes may be facing the same changes, particularly larger schemes covering a wide range of industries and workers. Different industries are likely to have different worker age and occupation profiles and therefore the impact of an ageing workforce is likely to differ across industries.

    Look beneath the surface of return-to-work rates

    There may be several contributing factors and reasons return to work can be difficult for older workers, including:

    • Less effective rehabilitation for people with chronic health conditions
    • A higher propensity for mental injuries, which have worse rates of return to work
    • It may be more difficult to find suitable duties for older workers to return to
    • People towards the end of their working career may have less incentive to return to work.

    A shift towards an older working population will likely result in a change in the frequency and mix of types of injuries.

    Higher claims incidence and poorer return-to-work rates may put more pressure on the financial stability of workers compensation schemes, however it’s important to assess the impact of an ageing claimant base on different benefit types. For example, incapacity benefits typically cease once a worker reaches the age pension age, whereas medical benefits usually extend beyond this age. There may be less pressure on incapacity benefits, with more claimants above the age pension age, but this might be offset by increased pressure on medical benefits.

    Forward-thinking approach to gain the benefits

    More research is needed to understand the impacts of the ageing workforce to date, in particular to identify if there’s a notable correlation between worker age and costs of workers compensation claims. It’s important schemes collect detailed data on age profiles of employees as well as claimants. This will support analysis of claims incidence, claims cost and return-to-work rates by worker age and occupation.

    It’s likely employers and industries will need to reform their occupational health and safety procedures to account for their older workforce and the associated risks.

    Governments could consider scheme changes to better address the needs of an ageing workforce, such as:

    • Increased focus on injury prevention and effective rehabilitation
    • Better management of long-term injured claimants
    • Assessing whether the current level of cross-subsidisation of premiums between employers with a younger workforce versus an older workforce is still appropriate.

    Despite the issues with an ageing workforce, research in recent years has explored the benefits of hiring older workers, such as higher levels of skills and experience, more employer loyalty and lower workplace absenteeism. By investing more in research and proactively designing scheme changes, Australia will be well placed to maximise its benefits from the ageing workforce, while minimising its risks.

  • How AI is transforming insurance

    2023 is the year artificial intelligence went mainstream for work, study and play. The insurance world has been quietly realising AI’s potential for years – to improve customer experience, increase efficiency and reduce costs. We explore what AI is bringing to the industry and where insurers can seize opportunity.

    Applications for AI in insurance span a range of operational areas, from pricing and underwriting through to customer interactions and claims processing. We break down how AI is being applied in key areas, where we’re seeing the biggest developments and what’s next for insurers.

    Boosting efficiency, accuracy and possibility in underwriting

    AI-led improvements in underwriting efficiency and practices are helping insurers boost sales opportunities by reducing the turnaround time for quotes, and improve risk assessment to support better pricing and profitability. In personal lines, where most customers purchase directly from an insurer, AI helps reduce the number of questions required in quote forms and, in certain cases, pre-fills questions. United States insurer State Farm and local player Suncorp, for example, use machine learning applied to geospatial images to streamline home insurance quoting and tie characteristics of the property to potential losses.

    AI helps reduce the number of questions required in quote forms and can sometimes pre-fill questions

    For commercial lines, where much of the underwriting process is manual, AI helps rapidly extract relevant information from documents. In the US, Liberty Mutual is demonstrating the benefits by applying natural language processing to documents to quickly extract relevant information to underwriters. This supports their conversations with brokers and customers, and halves the time required to extract loss data for mid-size and large accounts.

    More streamlined, effective claims assessment

    Image recognition helps simplify and streamline claims assessment, and supports enhanced digitisation of customer experience. This includes Aviva UK’s use of property and motor vehicle damage images to estimate repair costs, and IAG Firemark Venture’s recent investment in Ravin AI, an Israeli tech start-up. Ravin AI produces automated motor vehicle damage and repair cost estimates, which are based on customers’ mobile phone images.

    Moving beyond image recognition, natural language models, including large language models, are helping to extract relevant information from claims forms and notes. This increases the efficiency and effectiveness of claims teams, who can focus their time on claims requiring closer human review. For example, United Kingdom insurer RSA is applying this technology to claims from its pet insurance portfolio, automating the reading and extraction of relevant data from medical reports, treatments and progress notes.

    Chatbot makeovers for enhanced customer experience

    Most people are familiar with the artificial intelligence chatbot. Following recent advancements in large language models, such as those underpinning ChatGPT, the chatbot has benefitted from significantly enhanced capability and performance. Insurers employ these not only as direct-to-consumer instant messaging platforms to answer simple enquiries but also as ‘in house’ assistants to customer service centres.

    AI supports conversations with brokers and customers, and halves the time required to extract loss data for mid-size and large accounts.

    US-based Allstate Insurance’s ‘Amelia’, for example, leads call-centre employees through step-by-step procedures to help answer a variety of customer questions. Amelia also ‘listens’ to interactions she doesn’t understand, to expand her knowledge. Allstate says the benefits of Amelia include a reduction in the time taken to train new employees, and she’s also helping employees better comply with industry regulations.

    Innovations amid a warming world and a focus on bias

    With predicted investment in AI growing to $200 billion worldwide by 20251, we’re going to continue to see innovations in the insurance field. Budding research into AI for disaster prediction, management and relief is especially relevant for insurers in a warming world, with more frequent and intense weather events. In particular, researchers are developing frameworks that combine pre-disaster images with weather data and trajectory of hurricanes. These provide rapid insights on damage caused by natural disasters, with potential to assist in allocating resources for assessment, repair and disaster relief.

    Another strand of research looks to address potential bias and inequities introduced by AI pricing models. Discrimination-free pricing, for example, seeks to produce pricing models that avoid direct or indirect discrimination based on protected features such as gender, while maintaining overall model performance. This has been motivated in part by European Union regulation banning pricing discrimination based on protected attributes. We expect bias and fairness to become a focus of pricing models more globally, as insurers respond to rapidly developing government regulations and directives on the use and application of automated decision processes.

    Exciting times ahead, but risk management key

    While insurers have a lot to be excited about with the current and emerging uses of AI, it’s also a time to ensure systems and processes help them navigate the challenges posed by its use. AI processes can be brittle, exposing insurers to financial, regulatory, legal and reputational risks. Examples include financial losses driven by ‘rogue’ underwriting or pricing algorithms, legal penalties from breaches to customer privacy requirements and loss of goodwill from inequitable treatment of customers.

    Insurers will need to ensure their risk management practices are appropriately structured to incorporate, manage and mitigate AI-specific risks and provide a firm basis for meeting increasing regulatory and compliance requirements. These include impending government regulation on artificial intelligence and significant expansion of requirements under the Privacy Act. By expanding the legislation, the government aims to capture a much broader range of data-related practices, and increase customer rights to control how their data is used and stored.

    This article first appeared in RADAR FY2023, Taylor Fry’s annual roundup of Australia’s insurance landscape.